Medicare: A Federal Promise That Still Needs a Strategy
Medicare was created to make healthcare accessible for older Americans and those with qualifying disabilities. What it was not designed to do is explain itself clearly. And if you have ever tried to Google “Medicare Part A vs Part B vs Part C vs Part D,” you already know exactly what we mean. The information exists, but sorting through it without a guide is like navigating a new city with a map written in a foreign language.
Here is what matters most right now: Medicare is powerful coverage, but it has real gaps. The decisions you make during enrollment can follow you for years. And the good news is that with the right guidance, you can build a strategy that gives you genuine peace of mind, not just a card in your wallet.
What Medicare Actually Covers (And Who It Covers It For)
Medicare is a federal health insurance program primarily available to Americans age 65 and older, along with certain individuals under 65 who qualify through disability or specific medical conditions. If you or someone you love is approaching that milestone, this is one of the most important things to understand before the birthday arrives.
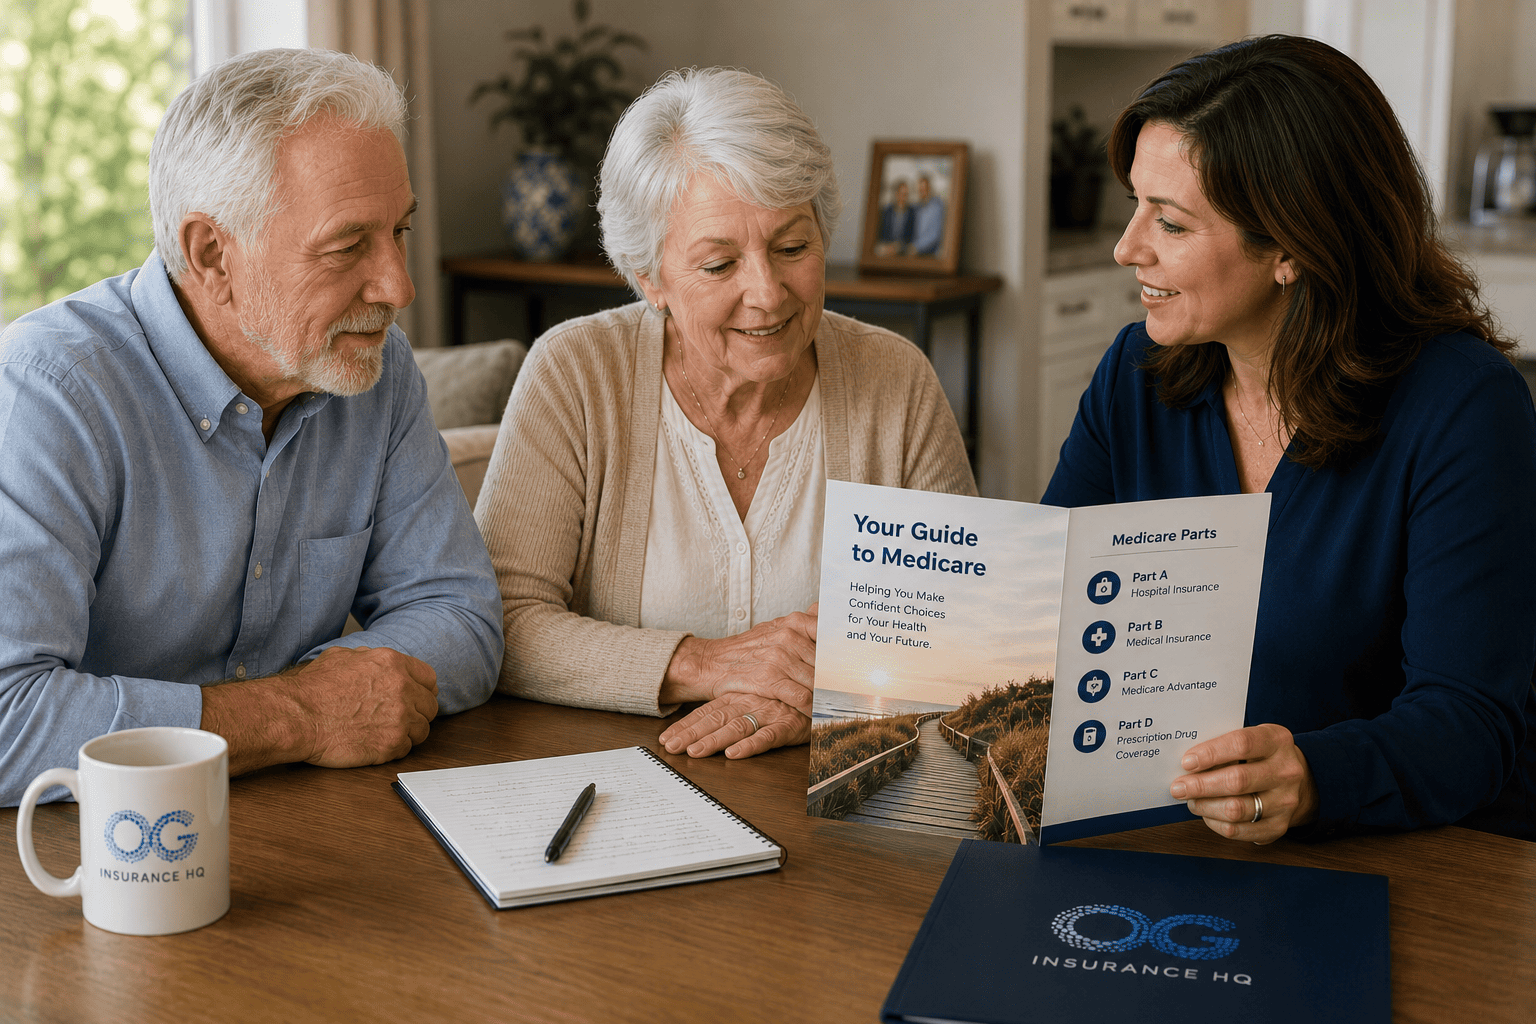
The program is organized into four parts, and understanding what each one does is the foundation of every smart Medicare decision.
Medicare Part A: Your Hospital Shield
Part A is hospital insurance. When you need inpatient care, a stay in a skilled nursing facility, hospice services, or certain home health support, Part A is the coverage doing the work. For most people who have worked and paid Medicare taxes for at least ten years, Part A comes with no monthly premium. That’s worth confirming before you assume you qualify.
Medicare Part B: Your Everyday Medical Coverage
Part B covers the things that happen outside the hospital: doctor visits, outpatient procedures, preventive screenings, lab work, durable medical equipment, and certain home health services. Part B does require a monthly premium, which is adjusted based on your income. It also has an annual deductible. Part B is not optional if you want to access most Medicare Supplement or Advantage plans, so understanding its costs is critical.
Medicare Part C: Medicare Advantage
Medicare Advantage is not a separate government program. It is an alternative delivery system. Private insurance companies approved by Medicare offer bundled plans that replace Original Medicare, often adding prescription drug coverage, dental, vision, and hearing benefits that Original Medicare does not include. Advantage plans have become very popular. They are worth understanding carefully, because they are not all the same.
Medicare Part D: Your Prescription Lifeline
Part D covers prescription drugs. If you take maintenance medications for blood pressure, cholesterol, diabetes, or anything else, Part D is not a luxury. It is a necessity. Standalone Part D plans are purchased alongside Original Medicare or Medigap. Many Medicare Advantage plans include Part D benefits. What you need to know: the right drug plan is the one that covers your specific medications at the lowest total cost, not just the one with the lowest premium.
What Medicare Does Not Cover (And Why That Matters)
This is where a lot of people get blindsided. Original Medicare does not pay 100 percent of your healthcare costs. Even after Medicare pays its share, you can still be on the hook for deductibles, coinsurance, and copays. And Original Medicare does not cover most dental care, routine vision, or hearing aids.
The result is that most Medicare beneficiaries need something more: either a Medicare Advantage plan that bundles additional benefits, or a Medicare Supplement policy that wraps around Original Medicare and covers many of those out-of-pocket gaps. Understanding which of those routes fits your life is the central question of Medicare planning.
The Two Big Choices: Advantage or Supplement?
This is the decision that shapes everything else. Medicare Advantage plans offer comprehensive bundled coverage, and some have low or $0 plan premiums (you still pay your Part B premium), but they work through provider networks and can vary significantly by geography and carrier. Medicare Supplement plans work alongside Original Medicare, giving you freedom to see any provider who accepts Medicare anywhere in the country, but they require a separate monthly premium.
Neither is universally better. The right answer depends on your health, your doctors, your medications, your travel habits, and your retirement budget. That is exactly why a personalized review matters more than a Google search.
The Enrollment Windows You Cannot Afford to Miss
Medicare has strict enrollment rules, and missing a deadline is not just an inconvenience. It can mean a late enrollment penalty that follows you for years. The Initial Enrollment Period is seven months long: the three months before the month you turn 65, your birthday month, and the three months after. Outside that window, you generally need a qualifying event to enroll without penalty.
There is also an Annual Enrollment Period each fall when you can review and change your coverage. It’s worth reviewing your coverage each year, because plans can change their costs, networks and drug lists.
Example (for Illustration): Margaret
Margaret turned 65 while still covered under her husband’s employer health plan. She assumed she could simply delay Medicare until she needed it. A few months later, her husband’s company downsized and she lost that coverage. She enrolled in Medicare at that point but had not planned for the transition. She ended up with a Part D late enrollment penalty because she had a gap in creditable drug coverage. The penalty was not large, but it will follow her for the rest of her life. A single planning conversation before her birthday could have prevented it entirely.
How OG Insurance HQ Helps
We do not hand you a brochure. We sit down with you and walk through your specific situation: your health history, your medications, your doctors, your retirement timeline, and your budget. We compare real plans with real numbers. And we are available every year during open enrollment to make sure your coverage still fits your life, because Medicare plans change whether you are paying attention or not.